

Payout: Claim Class Actions
4.9

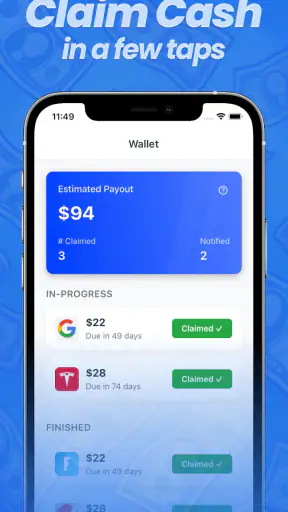
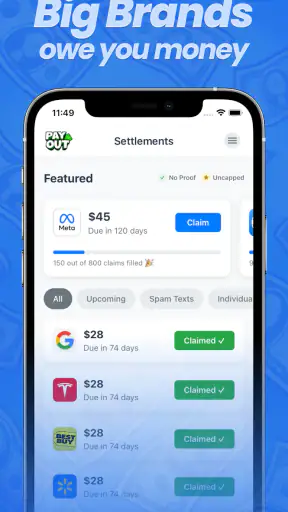
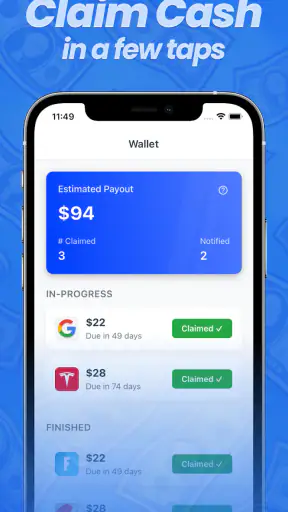
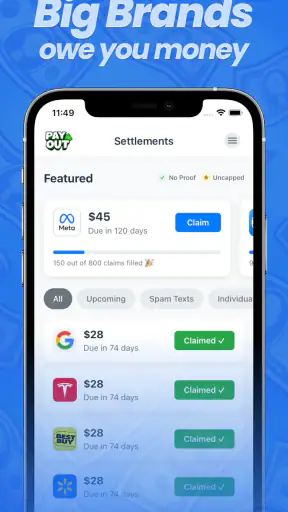
I approached Payout: Claim Class Actions as a household money app rather than as a guaranteed income source. Its basic appeal is easy to understand: it points people toward class-action claims that may offer compensation, with the promise of making the claiming process feel less intimidating. That can be useful when a family member hears about a settlement but does not know whether it applies to them or where to begin.
My first impression was that the app is aimed at quick access rather than long financial planning. It belongs in the finance category, is free to download, and is suitable for Everyone. The developer is PAYOUT LLC. Its store presence is strong, with a 4.9 average from around 9.7 thousand ratings and more than 100 thousand installs, which suggests that the concept has found an audience even though the app should still be approached with sensible expectations.
How it fits into a shared household
The most realistic use case is not passing one account around casually. It is using one person’s phone to investigate a possible claim, then stopping to decide whose information and experience actually belong in the application. For example, if a household receives a notice about a product or service involved in a settlement, one adult might open the app, review the opportunity, and compare the relevant dates or purchases with household records before anyone submits anything.
That distinction matters because a class-action claim is normally tied to an individual’s own experience, purchase, account, or eligibility. I would not treat a shared device as proof that every person in the home can claim through the same profile. Instead, I would use the app as a discovery and organization tool, while keeping each person’s claim details separate and accurate.
A practical routine is to create a small household checklist outside the app: who may have used the product, which email address belongs to that person, whether receipts or account records exist, and whether the relevant event happened during the period described by the claim. This avoids the common mistake of rushing because a possible payment sounds attractive. The quality of the information you submit matters more than how quickly you find a claim.
I also found that this kind of service is more useful for occasional checking than for constant attention. Class-action opportunities are not a dependable replacement for wages, and an app that helps identify claims cannot guarantee eligibility or payment. If you open it expecting regular income, the experience is likely to feel disappointing. If you use it to avoid missing a legitimate opportunity that fits your history, the value is easier to understand.
Keeping setup boundaries clear
Before setting up the app on a shared tablet or family phone, I would decide who is the actual account holder. The person whose information is being used should be involved from the beginning. A shared device does not need to become a shared financial identity, and mixing several people’s names, email addresses, purchase histories, or claim details can create confusion later.
My preferred arrangement would be simple: one adult reviews the app, each potential claimant checks their own eligibility, and only the relevant person supplies personal details when a claim genuinely applies. I would also avoid leaving an account open on a device that children or guests regularly use. Even with an Everyone content rating, financial information deserves a more careful boundary than ordinary entertainment apps.
The free download makes trying the service less of a commitment, but the app also lists in-app purchases ranging from $4.99 to $39.99 per item. That is the point where I would slow down and read every purchase screen carefully. A free installation does not mean every part of the experience is free, and a household should agree on whether any paid item is worthwhile before someone taps a purchase button.
I would never pay simply because a claim looks urgent or because a possible payout appears large. A fee can change the value of a small or uncertain claim, so the sensible comparison is between the total cost and the realistic benefit, not the headline amount. On a shared device, this is especially important because another family member may not realize that an in-app transaction is being made.
The current version is 4.0.4, and the app supports Android 7.0 or later. That makes compatibility relatively broad for older Android phones, but I would still check the device before planning to use it on an aging household handset. If the app is installed on a phone that several people rely on, keeping the operating system and app current is a basic way to reduce avoidable login or display problems.
Coordinating claims without duplicating work
Household coordination is where this app can be genuinely helpful, but only if the family treats it as a shared research task rather than a communal claim. Two people may notice the same settlement and accidentally prepare duplicate submissions, while another eligible person may be overlooked because nobody wrote down who was responsible for checking the details.
I would assign one person to review opportunities and another to verify the household records. The reviewer can note the claim name and deadline information shown in the app, while the second person checks receipts, order histories, emails, or other records. The final claimant should then make the submission using their own accurate information. This three-step separation—find, verify, submit—reduces both haste and accidental mixing of identities.
Another useful habit is to record the status of every opportunity in a private household note: “checking,” “not eligible,” “submitted,” or “waiting.” I would not store sensitive details in an open family chat, especially on a shared phone. The note only needs enough information to prevent duplicate effort. Once a claim has been submitted, the person who submitted it should remain responsible for watching any follow-up communication.
This workflow also answers a question many new users have: does finding a claim mean the app has already confirmed eligibility? I would not assume that. Discovery and eligibility are different steps. The app can make it easier to notice a possible opportunity, but the claimant still needs to read the requirements and make sure their own circumstances match them.
Compared with searching the web manually, the appeal here is convenience. A general search can produce scattered notices, outdated pages, and confusing legal language. A dedicated finance app may give the process a more approachable starting point. However, a direct settlement administrator page or official notice is still the better place to verify important terms, deadlines, and submission requirements before acting. I see the app as a filter and starting point, not as a substitute for reading the underlying claim information.
Age, trust, and personal information
The Everyone rating describes the app’s broad content suitability, not whether every financial decision is appropriate for every age group. In a household, I would let younger users observe the process only with an adult present, and I would not ask a child to enter payment, identity, or purchase information. The person making a claim should understand what they are submitting and why it belongs to them.
Trust is also important because a possible settlement can make people lower their guard. I would be cautious with any message that asks for sensitive details unexpectedly, creates pressure, or promises a payment without explaining the qualifying event. Even when an app is legitimate and useful, users should distinguish between information about a claim and requests from unrelated third parties.
For older relatives, the main benefit may be reducing the burden of searching and interpreting unfamiliar online information. I would sit with them, enlarge text if necessary, and read the eligibility language aloud rather than completing everything on their behalf. That preserves their control and makes it easier to catch an incorrect name, address, purchase history, or email account.
For roommates or friends sharing a device, the boundary should be even clearer. A roommate’s claim is not a household claim, and one person should not browse another person’s financial information without permission. The app can support coordination, but it does not remove the need for consent and individual responsibility.
Where it is useful and where I would skip it
I think this app is a good fit for someone who regularly forgets to check settlement opportunities, dislikes navigating legal notices, or wants one convenient place to begin researching possible compensation. It is also practical for a household that already keeps purchase emails and account records organized. In that situation, a quick review can lead to a sensible eligibility check instead of a random guess.
I would skip it if you need predictable income, instant cash, or a clear return for every minute spent. Class-action payments depend on eligibility, the claim process, and the outcome of the settlement, so the timing and value may not match your immediate needs. A budgeting app, savings tool, or legitimate work platform is a better choice when the goal is dependable financial planning or earnings.
I would also be careful if the household is likely to make impulsive in-app purchases. The listed purchase range means the free entry point should not be confused with an unlimited free service. If someone cannot comfortably review charges and decide whether they improve the process, staying with free access or using an official claim source may be the wiser route.
One non-obvious trade-off is convenience versus verification. The more streamlined the discovery process feels, the easier it is to forget that settlement language can contain important exceptions. Another is shared access versus privacy: a family can save time by coordinating, but it can also expose personal information if everyone uses the same unlocked phone. Finally, speed versus accuracy is a real choice here. Submitting quickly is not an advantage if the wrong household member submits or the details do not match the claim.
My household verdict
After looking at the app through a shared-use lens, I see it as a helpful claim-finding assistant with a narrow but worthwhile role. I would recommend it to an adult who wants a convenient starting point and is willing to verify every opportunity independently. I would not present it to family members as a money-making shortcut, and I would not let a shared device blur who owns the account or the claim.
The strongest setup is straightforward: keep the account boundary personal, use household records only to check eligibility, discuss any paid item before purchasing, and let the actual claimant control their submission and follow-up. That approach preserves the convenience while avoiding the most likely sources of trouble.
With its free download, Everyone rating, broad Android compatibility, and high user rating, the app is easy to try. Its value ultimately depends less on the number of opportunities it displays and more on whether you use it patiently. My recommendation is to treat Payout as a research shortcut, not a promise of cash. For careful users, that makes it a reasonable addition to a household finance routine; for anyone seeking guaranteed earnings or hands-off submissions, a different financial tool will be the better choice.
4.9
573.00 Reviews
Pros
- Searches a broad range of eligible class actions in one place.
- Provides claim deadlines to help users avoid missing filing windows.
- Explains settlement details before you decide whether to file.
- Claim forms can often be completed directly from your phone.
- Useful for discovering settlements you may not hear about elsewhere.
Cons
- Eligibility rules differ widely and may require proof of purchase.
- Some claims offer very small payments after final distribution.
- Settlement availability and deadlines can change without notice.
- Not every listed case guarantees a payout to approved claimants.
- Personal and payment information may be required for submissions.


